Investor and Multifamily Loans
How Do I Qualify for an Apartment Building Loan?
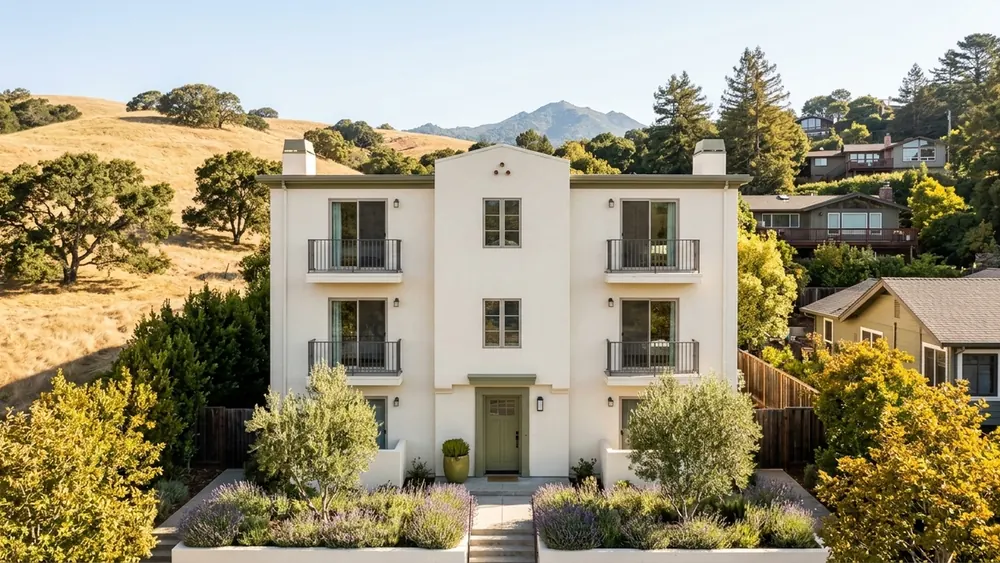
A building with five or more units is financed as multifamily or commercial real estate, so lenders focus first on the property’s net operating income and its ability to cover the debt. Your net worth, liquidity, credit and management experience also matter, and terms vary widely by program.
On this page
The short answer
Once a building has five or more units, it leaves the residential one- to four-unit world and is financed as multifamily or commercial real estate. Lenders look first at the property: how much income it produces after operating expenses, and whether that income comfortably covers the loan payments. Then they look at you: your net worth, cash on hand, credit and experience running rental property.
Financing can come from banks and credit unions, from lenders that offer Fannie Mae and Freddie Mac multifamily programs, or from private and bridge lenders. Each sets its own requirements, so the details below describe common practice, not fixed rules.
How lenders read the property’s income
Expect to provide a current rent roll listing every unit, its rent and lease dates, plus operating statements, often the trailing 12 months, and recent tax bills and insurance costs. From these, the lender estimates net operating income: the rent it expects to collect, minus vacancy and operating expenses such as taxes, insurance, utilities, repairs and management. Loan payments are not part of that figure.
Lenders generally underwrite their own numbers rather than a seller’s projections. They may assume a vacancy allowance, a management fee and replacement reserves even if you plan to manage the building yourself. Occupancy history matters, and so do the terms of existing leases and any state or local rent rules that limit future increases.
Debt service coverage and loan size
Debt service coverage compares net operating income with the annual loan payments. Lenders set a minimum ratio, and the loan amount is often the lower of what that ratio supports and what the maximum loan-to-value allows.
- Hypothetical, for illustration only: net operating income of $300,000 a year
- If a lender required a 1.25 ratio, annual payments could be up to $240,000
- If a lower loan-to-value limit produced a smaller loan, the smaller figure would usually apply
The 1.25 here is an assumption to show the math, not a requirement. Actual minimums vary by lender, program and property.
Property condition and due diligence
The appraisal for an apartment building relies heavily on the income approach. Lenders commonly require a physical inspection or property condition report, and often an environmental review. Deferred maintenance, building systems near the end of their life and needed repairs can reduce the loan amount or lead to required repair reserves. A building with high vacancy or major renovation plans may fit a bridge or renovation loan better than long-term financing.
Your financial strength and experience
Even when the property qualifies, lenders review the people behind it. Fannie Mae’s Multifamily Guide, for example, includes requirements for key principals, financial statements, and net worth and liquid assets. Many lenders ask for a personal financial statement, a schedule of real estate owned, credit reports, and proof of cash for the down payment, closing costs and reserves after closing.
Management experience matters. If you have not run a building this size, lenders may look for a professional property manager or experienced partners. Most of these loans are made to an LLC or other entity, and because they are business-purpose credit, the consumer disclosures that come with a home loan generally do not apply.
Down payment, terms, balloons and guarantees
Down payment and loan-to-value limits differ by program and are often driven by the coverage ratio. Many apartment loans have a term shorter than their amortization schedule, so a large balloon balance comes due at maturity. You would then need to refinance or sell, and neither is guaranteed: rates, the property’s income and lending conditions at that time will matter.
Prepayment terms are common and can be significant, including step-down penalties, yield maintenance or defeasance. Some loans are adjustable or interest-only for a period. Many bank loans require a full personal guarantee. Some agency programs are non-recourse, but they typically carry carve-outs for events such as fraud or misuse of funds that can still create personal liability. A real estate attorney and a tax professional can explain how a guarantee or entity structure affects you.
Talk it through with Jack Terrell
If you are looking at an apartment building anywhere in California, Jack Terrell, a mortgage broker and loan originator with California Mortgage Advisors, Inc. in San Rafael, can help you understand what lenders will ask for and compare multifamily and commercial options from more than one lender. Reaching out early, before you commit to a purchase, gives you the most room to plan.
This article provides general information about real estate financing in California. It is not a loan offer, pre-approval, commitment to lend, or personalized legal, tax, or financial advice. Programs, availability, terms, and eligibility requirements vary by lender, property, and borrower and may change. Review the disclosures and loan documents applicable to your transaction and consult a qualified professional for tax, legal, or estate-planning guidance.
Jack Terrell, Mortgage Broker and Loan Originator | NMLS #103232 | CA DRE #00992181
California Mortgage Advisors, Inc. | NMLS #1825 | CA DRE #01170868
Licensed by the California Department of Real Estate.
Equal Housing Opportunity
Written by